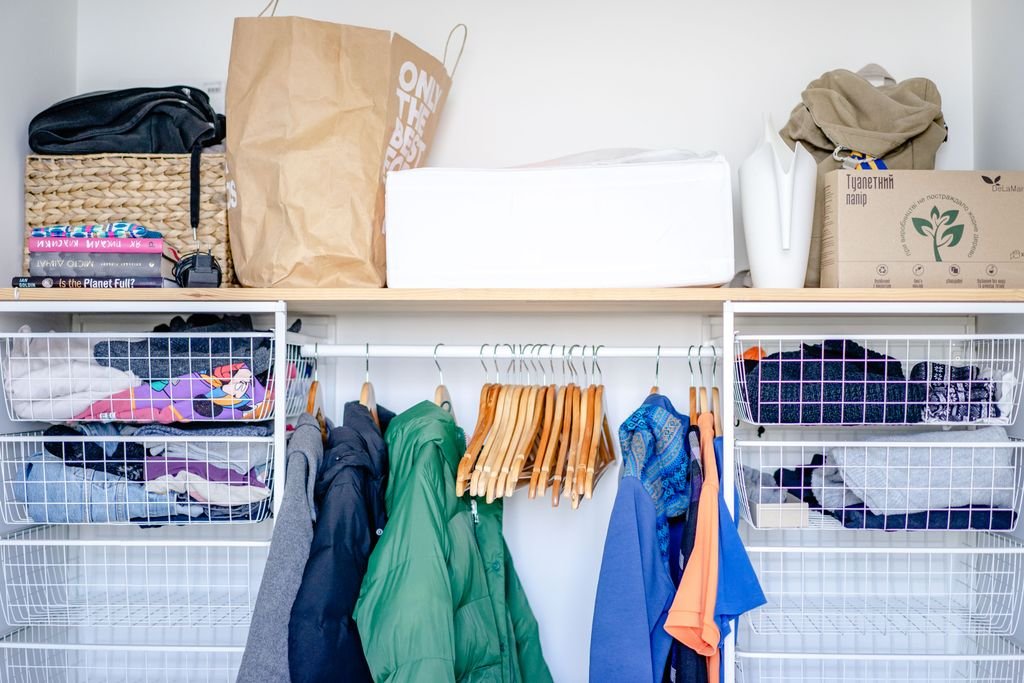
A clear wardrobe record starts with categories, counts and evidence.
Useful clothing categories for insurance appraisal include everyday garments, work and formal clothing, outerwear, footwear, accessories and specialty pieces. Organize those groups by household member and storage location, then record quantities, descriptions, age, condition and supporting documents.
These are practical organizing suggestions, not official categories required by every insurer. Your inventory can help you prepare for an insurance review or claim, but it does not establish coverage or guarantee a payment. A professional appraisal and an insurer’s claim valuation serve different purposes.
Inventory, Appraisal and Claim Valuation: Start With the Purpose
A home inventory is your record of the things you own. It can include photographs, receipts and estimated replacement prices. The NAIC’s home inventory guidance explains that grouping belongings by room or category and keeping images can help document property for a claim.
A professional appraisal provides an opinion of value for a defined assignment. If an insurer requests one for a valuable garment or collection, ask what qualifications, report format, valuation basis and effective date it will accept.
A claim valuation occurs after a reported loss. The policy’s covered causes of loss, valuation provisions, limits, deductible and evidence requirements affect the result. A well-organized spreadsheet is useful evidence; it does not replace the policy.
A Practical Clothing Category Checklist
Begin with one person and one closet or dresser. Use the following groups as a starting point, and add or remove subcategories to fit the household. Keep valuable or unusual items identifiable rather than burying them in a general total.
1. Everyday Clothing
- T-shirts, shirts and other tops
- Jeans, trousers, shorts and skirts
- Sweaters, cardigans and knitwear
- Casual dresses and everyday outfits
- Sleepwear, undergarments and socks
- Children’s clothing, separated by owner where helpful
Count individual garments or clearly defined sets. “Ten shirts” is more useful than “one drawer of clothes.” Separate substantially different quality levels so that one expensive shirt does not determine the estimate for an entire drawer.
2. Workwear and Formal Clothing
- Suits, blazers and tailored trousers
- Business shirts and professional outfits
- Formalwear and special-occasion garments
- Uniforms and occupational clothing
Record whether a suit is a complete set and note custom tailoring. For employer-owned uniforms or business inventory, identify ownership and ask which policy applies rather than assuming personal property coverage handles them.
3. Outerwear and Seasonal Items
- Winter coats, raincoats and jackets
- Snow gear and insulated layers
- Seasonal clothing stored in boxes or garment bags
- Specialty outerwear requiring individual documentation
Include off-season storage. A closet photographed in summer may leave expensive winter clothing undocumented. Record where those items are kept, including a separate storage unit, and ask about any location-related coverage restrictions.
4. Footwear
- Everyday shoes and sneakers
- Dress shoes, boots and sandals
- Work boots and sports-specific footwear
- Designer, rare or collectible pairs
Count shoes by pairs and state that unit in the inventory. List a collectible pair separately when authenticity, condition or scarcity materially affects its value.
5. Accessories and Related Wardrobe Items
- Belts, ties, scarves, hats and gloves
- Bags, wallets and other small leather goods
- Luggage and garment carriers
These items can be kept near the clothing section for convenience, but your spreadsheet category does not control how the insurer classifies them. Keep jewelry, watches and wearable electronics separately identifiable and ask about applicable special limits.
6. Specialty and Valuable Garments
- Bespoke tailoring and couture
- Wedding or ceremonial clothing
- Significant vintage garments
- Performance costumes and collectible fashion
- Furs or other unusually valuable pieces
Brand, materials, provenance, condition and replacement availability can matter. A high purchase price alone does not establish a universal appraisal requirement. Ask the insurer whether separate listing, an endorsement or a specialist appraisal is appropriate.
When Can You Group Items Together?
The Insurance Information Institute’s inventory guide recommends counting clothing by general category and identifying especially valuable pieces. That is a useful starting approach for a pre-loss household record.
Group routine items only when the description remains meaningful. For example, “six mid-range cotton work shirts, approximately one to three years old” is more informative than “shirts, $500.” Photograph the group and note differences that affect the estimate.
List distinctive items individually. A tailored suit, rare jacket or collectible bag deserves its own description and evidence. After a loss, an insurer may request more detailed itemization than your original grouped inventory, so retain the underlying photos and notes.
What to Record for Each Entry
Use a spreadsheet, an inventory app or a paper record with a secure backup. Useful fields include:
- Owner, category and storage location
- Item description, quantity and unit of count
- Brand, maker, fabric and identifying style information
- Approximate purchase date, original cost and condition
- Current comparable replacement price and research date
- Receipt, photograph, appraisal or other evidence reference
For a special piece, add alterations, authenticity documents, provenance and included accessories where relevant. Clothing often lacks a serial number; do not leave an item undocumented just because that field does not apply.
The NAIC’s homeowners and renters policy explanation recommends recording identifying details and supporting an inventory with receipts and photos. Keep original purchase cost separate from a current replacement estimate.
Replacement Cost Is Different From Resale Value
An old garment’s secondhand selling price may differ substantially from the cost of replacing it with a comparable new item. Neither number should automatically be treated as the claim payment.
The Washington insurance regulator’s home insurance explanation distinguishes replacement cost from actual cash value. Actual cash value generally accounts for depreciation; replacement-cost treatment follows the policy’s conditions and limits.
Our explanation of depreciated value and replacement coverage provides more detail. Ask whether actual replacement and proof of the expense are required to recover additional replacement-cost benefits, and what deadlines apply.
Do not apply an arbitrary depreciation percentage to every garment. Age, condition, policy provisions and the applicable claim process matter. An appraisal for insurance replacement also should not automatically be reused as a donation, estate or resale valuation.
A Simple Wardrobe Inventory Example
Consider a hypothetical inventory containing eight everyday shirts at an estimated comparable replacement price of $35 each, two coats at $180 each and three pairs of shoes at $90 per pair.
- Everyday shirts: $280 estimated replacement total
- Coats: $360 estimated replacement total
- Footwear: $270 estimated replacement total
- Combined planning estimate: $910
These are illustrative prices, not market averages or a claim settlement. Record the real quality, quantities and evidence rather than copying the example. A valuable tailored suit would be a separate entry instead of being averaged into everyday clothing.
When reviewing the household total, compare it with the amount of contents protection you need. Furniture, electronics and other possessions also use the overall limit; clothing does not necessarily have a separate pool of coverage.
Check Valuable Items and Policy Limits
Chubb’s wardrobe valuation guide highlights easily overlooked groups such as suits, coats, shoes, handbags and luggage. Several ordinary items can add up, while one specialty piece can require separate attention.
Ask your insurer how it treats valuable apparel, bags and furs, including any special limits or scheduling requirements. Ask what losses are covered, what exclusions apply and whether property in storage or away from home receives different treatment.
If the policy needs changing, our guide to adding or changing policy terms explains endorsements. An appraisal alone does not add coverage.
Keep Evidence Accessible After a Loss
Take wide photos of closets and drawers, then closer images of labels and individual valuables. Keep digital receipts and existing photos that show ownership. If a receipt is missing, preserve other truthful evidence and ask what the insurer accepts; never invent purchase dates or amounts.
NAIC disaster-preparedness guidance recommends keeping a backup somewhere other than the home. Secure cloud storage or another protected off-site copy can make records available if local devices are damaged.
Review the record after major purchases, moves or disposal of items. If a fire has already occurred, our explanation of documenting personal property after fire damage gives related context. Follow the insurer’s instructions before disposing of damaged property when safe to do so.
Frequently Asked Questions
Are these official insurance appraisal categories?
No. They are a practical organizing framework. The insurer or appraiser may require a different format for a particular assignment or claim.
Do all clothes need a professional appraisal?
Not necessarily. A documented household inventory can be a useful starting point for ordinary clothing. Ask about specialist appraisal requirements for unusually valuable or difficult-to-replace pieces.
Should I record original cost or replacement cost?
Keep separate fields for both when possible, along with age, condition and evidence. The relevant valuation basis depends on the assignment and policy.
Does an inventory guarantee reimbursement?
No. It supports documentation, but coverage, exclusions, limits, deductibles and claim conditions still determine payment.
This article provides general U.S. educational information, not individualized insurance, legal or appraisal advice. Confirm documentation and coverage requirements with your insurer and an appropriately qualified appraiser where needed.